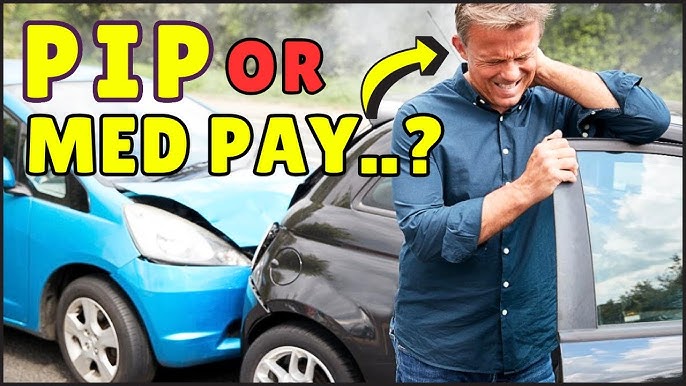
You are sitting at your kitchen table with the quote open, and two lines have stopped you cold: MedPay and PIP. Both promise to pay your medical bills after a crash. Both sound like the same thing. You are probably thinking: if they are the same, why are there two of them, and which one do I actually need?
Pick the wrong one, and you could be the person staring at a hospital bill your cover was supposed to pay. No jargon here, just the answer for you. What each one pays for, which one your state lets you buy, and which one fits your income, your health cover, and the people who ride in your car.
What MedPay does for you
MedPay, short for medical payments coverage, pays your medical expenses after a car accident, regardless of who caused it. It covers you, your passengers, and in many policies family members in your household. It can also cover you if you are hit as a pedestrian.
MedPay is narrow by design. It pays medical and funeral expenses, up to a limit you choose. Typical limits are low, often a few thousand dollars. That is enough for an emergency room visit and initial treatment, but not for a long hospital stay. If this is you, picturing a serious crash and a month in hospital, MedPay alone runs out long before your bills do.
MedPay does not pay for lost wages, childcare, or household help. It does not pay for pain and suffering. It is a small, simple, fast form of medical cover. It usually pays quickly, with little argument, because fault does not matter.
What PIP does for you
PIP, short for personal injury protection, is broader. It pays your medical expenses like MedPay, and it also pays your lost wages, and in many policies essential services such as childcare or household help while you recover. Some PIP policies also pay funeral expenses. You are probably thinking: lost wages, that is the part nobody talks about. Exactly. The hospital bill is not what breaks most families after a crash. The weeks without pay are.
PIP limits are usually higher than MedPay limits. That matters after a serious crash, where your medical bills and weeks off work can stack up fast. PIP is the main medical cover in no fault states, where you claim from your own insurer after a crash regardless of who caused it.
PIP has its own rules. It may require you to use certain providers. It may coordinate with your health insurance. And in some states, carrying PIP affects your right to sue for pain and suffering. Those details vary by state, so read your own policy wording before you decide.
The three differences that decide it for you
The first difference is scope. MedPay pays medical bills only. PIP pays medical bills plus lost wages and essential services. If you are self employed or the main earner in your household, that lost wage cover can matter more to you than the medical bills.
The second difference is limits. MedPay limits are usually small. PIP limits are usually larger. After a minor crash, either may be enough for you. After a serious one, MedPay alone often runs out fast and leaves you paying the rest.
The third difference is where they apply. PIP is tied to no fault insurance systems. MedPay is available in many states regardless of fault rules. In some states you can carry both, and MedPay can help with deductibles or gaps that PIP leaves. In others, one of them is not offered to you at all.
The National Association of Insurance Commissioners explains how no fault systems work and which states use them. Check it if you are unsure which system your state follows.
Which one your state lets you buy
About a dozen states use a no fault system for car accidents. In those states, PIP is usually required or strongly built into every policy. You claim from your own insurer first, whatever happened.
Most other states use a fault based system. The at fault driver pays, through their liability cover. In those states, MedPay is the common medical add on for you, and PIP may not be available at all.
A few states sit in between, offering PIP as an optional add on in a fault based system. This is where the confusion usually starts for you. Your insurer or agent can tell you exactly what is available on your policy, but it helps to know the question to ask: is this state no fault, fault based, or a hybrid, and what medical cover does that mean for me?
Which one fits your life
If PIP is required in your state, the decision is made for you. Take the required limits, then ask whether higher limits are worth it given your income and your health insurance. If you are the main earner, higher PIP limits are worth a serious look.
If MedPay is the option, ask whether your health insurance already covers car accident injuries well. If it does, with a low deductible and a broad network, MedPay may be a modest top up. If your health cover is thin, has a high deductible, or excludes car accidents, MedPay is worth more to you. You are probably thinking: my health insurance covers me, so why pay twice? Because your health insurance has never met your passengers, and that is the next thing to face.
Your passengers matter too. MedPay and PIP both typically cover passengers, which your health insurance does not. If you regularly drive friends, family, or children, medical cover on the car policy protects people your health plan never will. Our guide on what full coverage car insurance means explains how these medical sections fit into the wider policy.
Does your health insurance already cover this
You may be assuming your health insurance makes car medical cover redundant. Sometimes it does. Often it does not. Your health insurance may not cover your passengers. It may have a high deductible that car medical cover can help meet. It may require pre authorisation for treatment that a crash makes urgent.
Coordination of benefits also matters. In some states and policies, PIP pays first and health insurance pays second. In others, health insurance pays first. The order affects how much you pay out of pocket and how fast bills are settled. Ask your insurer which applies to your policy.
Do not drop your health insurance because you have PIP, and do not drop PIP because you have health insurance, without checking the overlap properly. The two cover different people in different ways, and the gap only shows up after a crash.
What happens when you actually claim
After a crash, get medical help first. Everything else can wait. Once you are safe, report the crash to your insurer and tell them you may need medical cover. Keep every bill, receipt, and medical record. If your PIP covers lost wages, keep proof of your income and time off work.
MedPay claims are usually straightforward. Submit the bills and the insurer pays up to the limit. PIP claims can take longer, because lost wages and ongoing treatment need documentation. Stay in contact with the adjuster and respond to requests promptly. Delays usually come from missing paperwork, not from disputes.
If fault is disputed or injuries are serious, the claim can take longer still. Our guide on how to file a car insurance claim properly walks through the process step by step.
For timelines and what to expect while the claim moves forward, see our guide on what happens after a car insurance claim.
Your decision
Start with what your state requires. Then look at your health insurance, your income, and who rides in your car. If PIP is available and you are the main earner, it is usually the stronger choice for you. If MedPay is the option, take enough to cover your health deductible and the immediate costs of an emergency visit. If this is you, the main earner with a family in the car and a high health deductible, the minimum limits are not a bargain. They are a bet that your crash will be small.
Price both. MedPay is usually cheap. PIP costs more, but it covers more. The right choice for you is not the cheapest line on the quote. It is the one that leaves you able to get treatment and pay your bills after a real crash.
The Insurance Information Institute publishes plain explanations of both cover types. If an agent describes one of them in terms that do not match what you read here, ask for the policy wording.
Frequently Asked Questions
Is PIP better than MedPay?
PIP covers more for you: medical bills plus lost wages and essential services, with usually higher limits. MedPay covers medical bills only, with lower limits. Which is better for you depends on your state, your income, and your health insurance.
Can I have both MedPay and PIP?
In some states yes. MedPay can then help with deductibles or gaps that PIP leaves. In other states only one is offered. Ask your insurer what your state allows and whether carrying both is worth the extra premium.
Does MedPay cover lost wages?
No. MedPay pays medical and funeral expenses only. If you need lost wage cover after a crash, you need PIP or another form of income protection. This is the biggest practical difference between the two for you.
Does PIP cover passengers?
Yes, PIP and MedPay both typically cover your passengers, as well as you. This matters because your health insurance does not cover your passengers. If you regularly drive others, medical cover on the car policy protects them.
Do I need medical cover if I have health insurance?
Often yes, at least in some amount. Your health insurance may not cover your passengers, may have a high deductible, or may exclude car accident injuries. Car medical cover fills those gaps and usually pays faster after a crash.
So here is where you stand. MedPay is small and fast. PIP is broader and stronger. Your state decides which are on the table, and your income, health cover, and passengers decide which one you need. Before you accept your next quote, check which one your state offers you, then pick the one that would actually pay your bills after a real crash. That single check is the whole point.